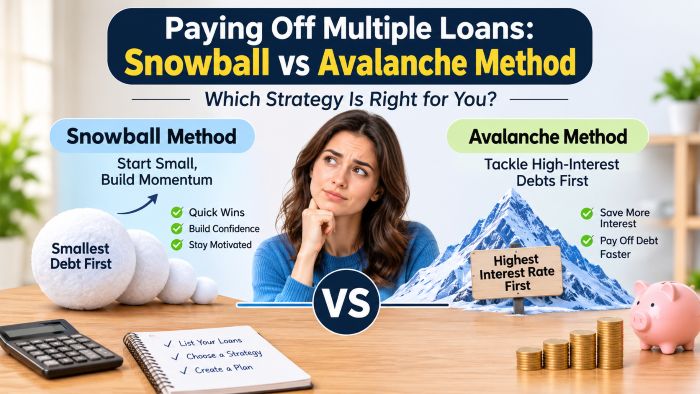
Juggling a credit card balance, a personal loan and a consumer EMI can feel overwhelming. When you have more than one debt and some extra money each month, the big question is: which one should you pay off first? Two popular strategies answer it differently.
The basics: minimums first
Whichever method you choose, always pay the minimum due on every loan and card to avoid late fees and damage to your credit score. The strategy is about where to send any extra money.
The avalanche method: highest interest first
Put all extra money toward the debt with the highest interest rate. Once it’s paid off, move to the next-highest rate.
Why it works: it minimises the total interest you pay, so it’s mathematically the cheapest option.
Downside: if your highest-rate debt is also large, it can take a long time before you clear your first loan, which can feel discouraging.
The snowball method: smallest balance first
Put all extra money toward the smallest balance, regardless of interest rate. Once it’s gone, roll that payment into the next-smallest.
Why it works: quick wins build motivation, and fewer accounts make life simpler.
Downside: you may pay more interest overall if larger debts carry higher rates.
Example
Suppose you have three debts and 10,000 a month extra to put toward them:
| Debt | Balance | Interest rate |
|---|---|---|
| Credit card | 80,000 | 36% |
| Personal loan | 1,50,000 | 14% |
| Consumer EMI | 20,000 | 16% |
- Avalanche order: credit card → consumer EMI → personal loan
- Snowball order: consumer EMI → credit card → personal loan
Here, the avalanche saves more because the credit card’s rate is far higher. The snowball gives you a quicker first win by clearing the EMI in about two months.
High-interest debt grows quickly because interest compounds on unpaid balances. To get a feel for how fast, see how interest compounds over time at a credit card’s rate versus a savings rate.
Which method should you choose?
| If you… | Consider… |
|---|---|
| Stay motivated by numbers and savings | Avalanche |
| Need early wins to keep going | Snowball |
| Have one very high-interest debt (like a card) | Avalanche, at least for that debt |
| Feel overwhelmed by many small accounts | Snowball |
The best method is the one you’ll stick with. A hybrid works too: clear one tiny balance for a quick win, then switch to the avalanche.
Speed things up
- Stop adding new debt while you repay.
- Use windfalls: bonuses and refunds can knock out a debt quickly.
- Negotiate rates: ask lenders about lower rates or balance transfer offers, reading the fees carefully.
- Consider consolidation: a single lower-interest loan can replace several expensive ones, if the total cost is genuinely lower.
- Keep a small emergency fund so surprises don’t send you back to credit cards.
Frequently asked questions
Should I invest while paying off debt?
If the debt’s interest rate is higher than what investments are likely to earn, paying off debt usually comes first.
Does closing a paid-off credit card help my score?
Not necessarily. Keeping an old card open with zero balance can help credit history and utilisation.
What if I can’t pay even the minimums?
Contact lenders early to discuss restructuring, and consider speaking with a credit counsellor.
Final thoughts
Avalanche saves the most money; snowball builds the most momentum. Pick one, automate your payments and celebrate each debt you clear.